
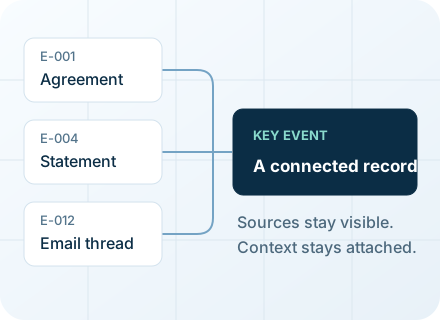
The record, in perspective.
The supplied agreement establishes the starting scope. An invoice and statement share a payment reference. Later communications discuss revised timing and work in progress, followed by a request for clarification. The record set does not establish whether the revised date was accepted or whether the work was delivered. The client’s later summary is retained as an account, separately from the underlying records.
Swipe or scroll horizontally to view the full table
| Date | Event & context | Source |
|---|---|---|
| April 03 | Scope of work signed. Starting terms appear in the agreement. | E-001 |
| April 08 | Initial invoice issued with a reference later appearing on the payment record. | E-005 |
| April 12 | Initial payment recorded. Statement reference matches the invoice. | E-004, E-005 |
| April 24 | Revised delivery date discussed. Written acceptance not supplied. | E-012 |
| April 29 | Progress message references work underway; no delivery attachment is included. | E-016 |
| May 02 | Client asks for clarification of timing and remaining work. | E-019 |
| May 06 | Status summary lists an unresolved delivery question. It is a client account, not independent confirmation. | E-021 |
Swipe or scroll horizontally to view the full table
| Reference | Record | Factual subject |
|---|---|---|
| E-001 | Signed scope of work | Agreement |
| E-004 | Bank statement excerpt | Payment |
| E-005 | Initial invoice | Payment |
| E-012 | Email thread | Delivery timing |
| E-016 | Progress message · April 29 | Work status |
| E-019 | Clarification email · May 02 | Timing and remaining work |
| E-021 | Client status summary · May 06 | Client account / open questions |
Was the revised date confirmed?
The email references a change in timing. Written acceptance and a complete follow-up thread are not included. The gap register below records what remains unclear and the material that could help resolve it.
One event. Several connected records.
The statement entry and invoice share a reference. Together they provide more context than either document viewed alone.
Invoice referenceE-004
Statement entryApril 12
Timeline event
- What the records show
- A recorded payment linked to the initial invoice by reference.
- What they do not establish
- Completion of the work, acceptance of delivery or agreement to revised timing.
- Why this distinction matters
- Payment and delivery are separate factual questions. The report preserves that distinction for the reader.
Find the subject, then follow the source.
Starting terms and stated deliverables.
E-001 · AgreementInvoice and statement reference connection.
E-004 + E-005Original date, proposed change and missing confirmation.
E-001 + E-012Keep open questions actionable.
Confirmation of revised timing
Trigger: E-012 refers to a proposed change; the supplied thread does not show acceptance.
Material to check: Any complete follow-up thread already in the client's possession.
Limit: Absence from this record set does not establish that confirmation never occurred.
Review status: Awaiting additional client-provided material. No third-party contact is included.
Delivery material
E-016 mentions progress, but no completed-work attachment or delivery receipt appears in the example record set.
Check: Supplied attachments, transfer notices and related files.
Complete communication chain
E-019 asks for clarification. The set does not include a response resolving the timing and remaining-work questions.
Check: Any later correspondence already held by the client.
Follow how the discussion changes.
A sequence of messages can reveal where the subject shifts, where clarification is requested and where the available record stops.
Separate a payment trail from a delivery question.
Where relevant to the agreed scope, the analysis connects supplied financial records without treating them as proof of unrelated events.
No amount, balance due or loss is inferred in this example. A full reconciliation would depend on the relevant statements, invoices and adjustments supplied.
Make the strength of the record visible.
E-001 records the starting agreement. Later changes require their own supporting material.
E-004 and E-005 share a reference. The match is useful but does not answer every payment or delivery question.
E-012, E-016 and E-019 show parts of a conversation. Missing replies and attachments remain visible limitations.
E-021 summarizes the client’s understanding. It is identified as an account and compared with supplied records.
Organization and analytical review do not authenticate documents, determine admissibility or establish legal conclusions.
The essential picture, ready for review.
Agreement and payment are linked.
Timing and delivery remain open.
- Established in this set: Starting scope and a payment reference connection.
- Developing sequence: Proposed timing change, progress message and clarification request.
- Unresolved: Acceptance of revised timing, delivery material and follow-up correspondence.
- Reader’s route: Review the chronology, follow the evidence IDs and check the three recorded information gaps.
Prepared as an analytical overview for discussion with your professional adviser. Legal significance remains for counsel to assess.